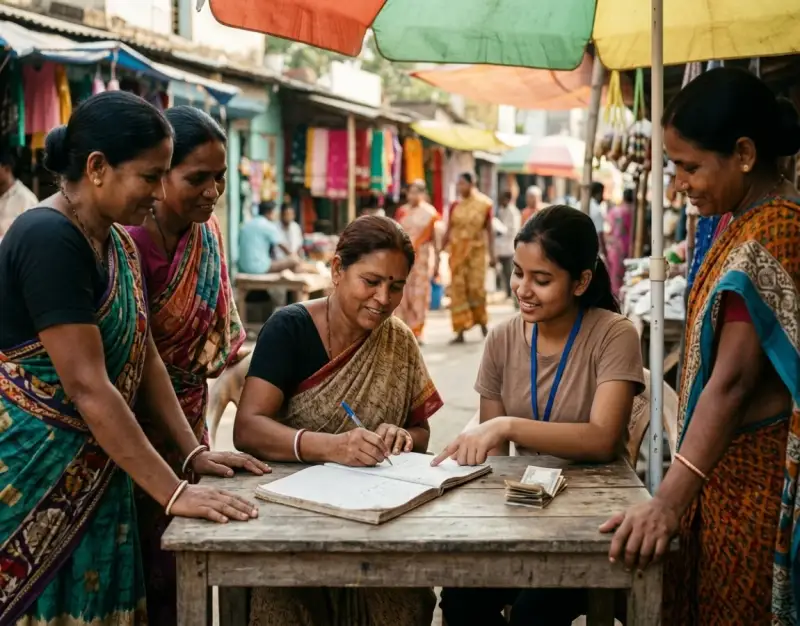
For decades, traditional financial institutions have operated on a premise of exclusion: to receive capital, one must already possess capital. This systemic barrier has historically locked marginalized populations, under-resourced urban corridors, and forgotten rural hamlets out of the formal economy. Yet, a quiet financial revolution is actively dismantling these century-old barricades. Across the globe and increasingly within localized neighborhoods, grass-roots micro-lending initiatives are providing the spark needed to ignite local enterprise, restore neighborhood dignity, and fuel comprehensive poverty alleviation.
This movement is far more than a charitable endeavor; it is a sophisticated economic engine rooted in trust, peer accountability, and radical accessibility. When local entrepreneurs receive small, unsecured loans coupled with technical mentorship, the financial ripple effects extend far beyond a single balance sheet. Families secure stable housing, children stay in school longer, and neglected commercial corridors transform into vibrant hubs of commerce. As economic landscapes shift, understanding the nuances of these financial interventions becomes crucial for anyone dedicated to uplifting communities through sustainable, market-based solutions.
At Caring Connections, our investigative deep-dives continually reveal that the most enduring socio-economic transformations do not trickle down from corporate boardrooms—they bubble up from the streets. By examining the precise mechanics of modern micro-lending programs, unpacking the psychology of grassroots financial support, and charting strategic roadmaps for implementation, this comprehensive guide will illuminate how small loans are generating monumental community wealth.
Understanding the Architecture of Grassroots Micro-Lending
The Evolution from Global Models to Hyper-Local Neighborhoods
The contemporary micro-lending movement traces its philosophical roots to pioneering global initiatives that demonstrated how unbanked individuals could responsibly manage tiny loans to build sustainable livelihoods. However, replicating these models in industrialized urban centers and rural pockets required a fundamental reinvention. Today’s localized programs discard rigid bureaucratic lending criteria in favor of hyper-local context awareness. Organizers recognize that a bodega owner in an economically depressed urban core faces vastly different systemic hurdles than an agricultural worker in a developing region, necessitating tailored financial toolkits.
This evolution has been accelerated by digital financial infrastructure, which reduces transaction friction and administrative overhead. Where paper ledgers and weekly in-person cash collections once dominated, secure digital ledger systems and mobile payment integrations now allow micro-lending funds to disburse capital within hours. This modernization ensures that grassroots financial support remains nimble, responsive, and deeply integrated into the day-to-day realities of the neighborhoods it serves.
Core Principles Driving Sustainable Poverty Alleviation
True poverty alleviation through micro-lending cannot occur through capital injection alone; it requires an ecosystem built on dignity, financial literacy, and holistic empowerment. Traditional predatory lenders capitalize on desperation by imposing exorbitant interest rates and opaque fee structures. In stark contrast, ethical micro-lenders operate on principles of transparency, capping interest rates at sustainable operational thresholds and structuring repayment schedules to match seasonal or weekly cash flows of micro-businesses.
Furthermore, these programs prioritize relational capital over transactional volume. Loan officers and community organizers act as mentors rather than collection agents. They provide continuous guidance on inventory management, digital marketing, and basic bookkeeping. This dual approach—supplying both the financial oxygen and the operational know-how—ensures that borrowers do not just survive temporary crises, but build resilient, multi-year business enterprises.
The Strategic Blueprint for Establishing Neighborhood Micro-Funds
Phase 1: Community Needs Assessment and Stakeholder Mapping
Launching a successful micro-lending initiative begins long before a single dollar is loaned; it demands rigorous, empathetic listening. Organizers must conduct comprehensive community needs assessments to identify existing economic gaps, dominant informal economies, and cultural nuances that dictate financial behavior. Engaging local leaders, religious institutions, existing business owners, and residents ensures that the program addresses actual community pain points rather than external assumptions.
Stakeholder mapping during this phase identifies potential partners who can amplify reach and credibility. By collaborating with trusted community anchors—such as neighborhood community centers, grassroots non-profits, and socially conscious credit unions—new micro-funds can bypass the skepticism often directed at outside financial entities. This foundational trust is the bedrock upon which high repayment rates and genuine community buy-in are constructed.
Phase 2: Capital Sourcing and Sustainable Funding Models
Securing initial capital for grassroots micro-lending programs requires a diversified funding matrix that balances grants, philanthropic donations, and impact-investing capital. Relying solely on volatile government grants or unpredictable charitable donations can jeopardize the long-term viability of a fund. Instead, pioneering organizations establish revolving loan funds where repaid principal and modest interest are immediately redeployed to fund new neighborhood entrepreneurs.
To scale operations without sacrificing mission integrity, practitioners increasingly utilize peer-to-peer digital crowdfunding platforms and impact bonds. These modern funding mechanisms allow everyday citizens to invest directly in specific neighborhood businesses, creating a profound sense of shared destiny. When a local resident contributes twenty-five dollars to help a neighbor launch a catering service, they become an active stakeholder in that neighborhood's economic renaissance.
Operationalizing Peer Support and Collective Accountability
The Power of Solidarity Lending Circles
One of the most profound innovations in micro-lending is the utilization of solidarity lending circles—small peer groups of four to eight entrepreneurs who mutually guarantee each other’s loans. Without requiring traditional collateral like real estate or automobiles, these circles leverage social capital as security. If one member experiences a temporary cash flow disruption, the group collaboratively strategizes to cover the payment, offering both financial cushion and emotional resilience.
This collective accountability structure transforms borrowing from an isolating, anxiety-inducing transaction into a community-building exercise. Peer groups naturally enforce discipline, share best practices, and celebrate milestones together. The psychological impact is transformative: individuals who have been marginalized by formal banking systems realize that their peers trust them, and that their success or failure directly influences the well-being of their friends and neighbors.
Integrating Comprehensive Financial Literacy Curricula
Capital without education is a temporary fix that can inadvertently lead to over-indebtedness. Consequently, leading micro-lending initiatives mandate or heavily incentivize participation in tailored financial literacy modules. These workshops cover practical, immediate applications: separating personal and business finances, understanding cash flow forecasting, optimizing pricing strategies, and establishing personal credit scores.
Importantly, these educational sessions are designed to be conversational and culturally responsive, moving away from intimidating academic jargon. By demystifying financial concepts, programs empower borrowers to make informed decisions that protect their enterprises against macro-economic shocks. Over time, this education fosters generational wealth-building mindsets, ensuring that the benefits of an initial micro-loan ripple across families for decades.
Navigating Regulatory Landscapes and Ethical Safeguards
Compliance, Licensing, and Protecting Vulnerable Borrowers
Operating a micro-lending program within legal boundaries requires meticulous navigation of local, state, and federal lending regulations. Depending on the jurisdiction, organizations must secure specific non-profit statuses, microlender licenses, or partner with chartered financial institutions to legally disburse funds. Ignoring these regulatory frameworks exposes programs to severe legal liabilities and can jeopardize the very communities they seek to protect.
Ethical safeguards must be codified into the organization's charter. This includes establishing strict protocols for handling defaults that prioritize restructuring and compassionate intervention over aggressive asset seizure or predatory collection tactics. Transparency in loan disclosures, zero hidden fees, and absolute data privacy protection are non-negotiable pillars that maintain institutional integrity and safeguard vulnerable borrowers from exploitation.
Measuring Impact Beyond Repayment Rates
While financial sustainability—measured by portfolio-at-risk and repayment rates—is vital, it tells only half the story. True poverty alleviation requires a sophisticated, holistic impact measurement framework. Programs must track qualitative and quantitative metrics that capture the broader socio-economic transformation of the neighborhood, such as household income growth, job creation rates, housing stability indices, and educational attainment improvements among borrowers' children.
Utilizing digital tracking tools and periodic longitudinal surveys allows organizations to continuously refine their methodologies. When leadership can empirically demonstrate that every dollar invested yields measurable improvements in community health, educational outcomes, and local employment, securing ongoing philanthropic and institutional support becomes significantly more sustainable.
Real-World Case Studies: Triumph Versus Pitfall
Case Study A: The Urban Corridor Revival
Consider the revitalization of a historically under-invested commercial district in the Midwest. A coalition of community organizers launched a localized micro-lending fund targeting immigrant entrepreneurs who were locked out of traditional commercial loans due to credit history gaps and language barriers. Providing average loans of $3,500 paired with bilingual business coaching, the fund backed thirty diverse enterprises in its first eighteen months.
The results were staggering: within three years, twenty-eight of the thirty businesses remained operational, collectively employing over ninety local residents. Vacant storefronts transformed into vibrant bakeries, tailor shops, and tech repair kiosks. More importantly, the neighborhood crime rate dropped by fifteen percent as foot traffic increased and local youth secured after-school employment opportunities. This case exemplifies how targeted grassroots financial support can catalyze organic urban renewal without displacement.
Case Study B: The Pitfall of Rapid Scaling Without Infrastructure
Conversely, a cautionary tale emerges from an ambitious regional micro-lending initiative that attempted to scale nationwide within twelve months, fueled by a sudden influx of corporate venture capital. Driven by aggressive growth metrics, the organization abandoned its mandatory peer-support circles and replaced localized, relationship-driven underwriting with an automated, algorithm-driven approval process.
Without human oversight and community-level trust verification, loan defaults skyrocketed past thirty-five percent within a single fiscal quarter. The algorithmic models failed to capture the nuanced economic realities of informal workers, resulting in misallocated capital and severe financial distress for borrowers who could not realistically manage the repayment terms. The organization was forced to restructure, shedding staff and abandoning dozens of communities that had grown to rely on their support. The critical lesson: micro-lending cannot be aggressively commodified without losing its soul and its efficacy.
Critical Mistakes to Avoid in Neighborhood Micro-Lending
- Neglecting Cultural Context: Imposing rigid, standardized lending models across diverse neighborhoods without adapting to local cultural norms, languages, and business practices invariably leads to low engagement and high default rates.
- Treating Loans as Pure Charity: Failing to enforce structured repayment terms or abandoning accountability mechanisms transforms the micro-fund into a short-term handout, depleting capital reserves and eroding borrower discipline.
- Overlooking Post-Disbursement Support: Issuing capital without pairing it with ongoing mentorship, bookkeeping training, and operational guidance leaves vulnerable entrepreneurs unequipped to navigate market volatility.
- Ignoring Regulatory Compliance: Operating outside established lending laws or failing to secure proper licensing exposes the organization to catastrophic legal challenges and undermines community trust.
- Chasing Vanity Metrics: Prioritizing sheer loan volume or rapid expansion over the depth of impact and financial health of individual borrowers compromises the core mission of sustainable poverty alleviation.
Comparative Analysis of Community Financial Models
| Financial Model | Primary Objective | Collateral Requirement | Interest Rate Structure | Support Services |
|---|---|---|---|---|
| Traditional Commercial Bank | Profit maximization for shareholders | High (Real estate, liquid assets, heavy credit checks) | Market-rate to low-prime | Minimal to none for small accounts |
| Payday / Predatory Lenders | Short-term extraction of high fees | None (High-risk interest substitution) | Extremely high (often 300%+ APR) | Non-existent / predatory collection tactics |
| Grassroots Micro-Lending Fund | Poverty alleviation & community wealth | Social capital / Solidarity circles | Low, transparent, operational cost-recovery | Extensive (Mentorship, financial literacy, peer support) |
| Peer-to-Peer Crowdfunding | Direct donor-to-entrepreneur connection | Minimal / Reputation-based | Varies (Often 0% to low-interest) | Community hype and marketing exposure |
Frequently Asked Questions
What distinguishes micro-lending from traditional micro-finance?
While micro-finance is a broad umbrella term encompassing various financial services—including insurance, savings accounts, and large-scale micro-credit—micro-lending specifically focuses on the disbursement and collection of very small business loans. Furthermore, modern grassroots micro-lending places an intense emphasis on hyper-local community integration, peer support circles, and comprehensive mentorship, moving beyond mere financial transactions to drive holistic neighborhood transformation.
How do micro-lending programs handle defaults without destroying community trust?
Ethical micro-lending programs utilize proactive communication and flexible restructuring rather than punitive collection measures. By employing solidarity lending circles, peer groups often help members navigate temporary hardships before defaults occur. When legitimate defaults happen, programs typically re-evaluate the business plan, offer grace periods, or absorb losses through designated risk reserves, ensuring that the borrower's dignity and community standing remain intact.
Can anyone launch a neighborhood micro-lending initiative?
While passionate individuals can spark the initial vision, successfully launching and sustaining a micro-lending fund requires legal compliance, financial management expertise, and deep community roots. Founders must collaborate with legal professionals, establish robust governance structures, and secure compliant funding partnerships to ensure the initiative operates ethically and sustainably over the long term.
What role does technology play in modern micro-lending?
Technology has revolutionized grassroots finance by streamlining application processes, enabling mobile money transfers, and reducing administrative overhead. Secure digital platforms allow micro-funds to track repayment metrics in real-time, disburse funds rapidly during economic emergencies, and connect remote donors directly with neighborhood entrepreneurs, scaling impact without sacrificing relational integrity.
How can local residents participate if they cannot afford to fund a loan?
Financial contribution is only one way to support the micro-lending movement. Residents can offer their professional skills—such as accounting, legal advice, graphic design, or marketing—as pro-bono mentors to micro-entrepreneurs. Additionally, simply choosing to patronize newly established local businesses and spreading word-of-mouth advocacy provides invaluable support that directly fuels neighborhood economic resilience.
Strategic Roadmap and Final Takeaways
The micro-lending movement represents a profound paradigm shift in how society approaches economic empowerment. By rejecting the exclusionary gatekeeping of traditional banking and embracing the power of grassroots financial support, communities are successfully proving that poverty is not an immutable condition, but a structural challenge that can be solved through localized investment and human connection. As we look ahead to the next two to five years, the integration of ethical digital tools with hyper-local relational frameworks will only accelerate this transformation.
For practitioners, community leaders, and change-makers, the mandate is clear: build systems rooted in trust, prioritize holistic education alongside capital, and measure success not just in dollars repaid, but in lives uplifted. When we invest in the smallest enterprises of our most overlooked neighbors, we lay the unbreakable foundation for thriving, resilient communities that benefit everyone.
Be the first to share a gentle reflection on this story.